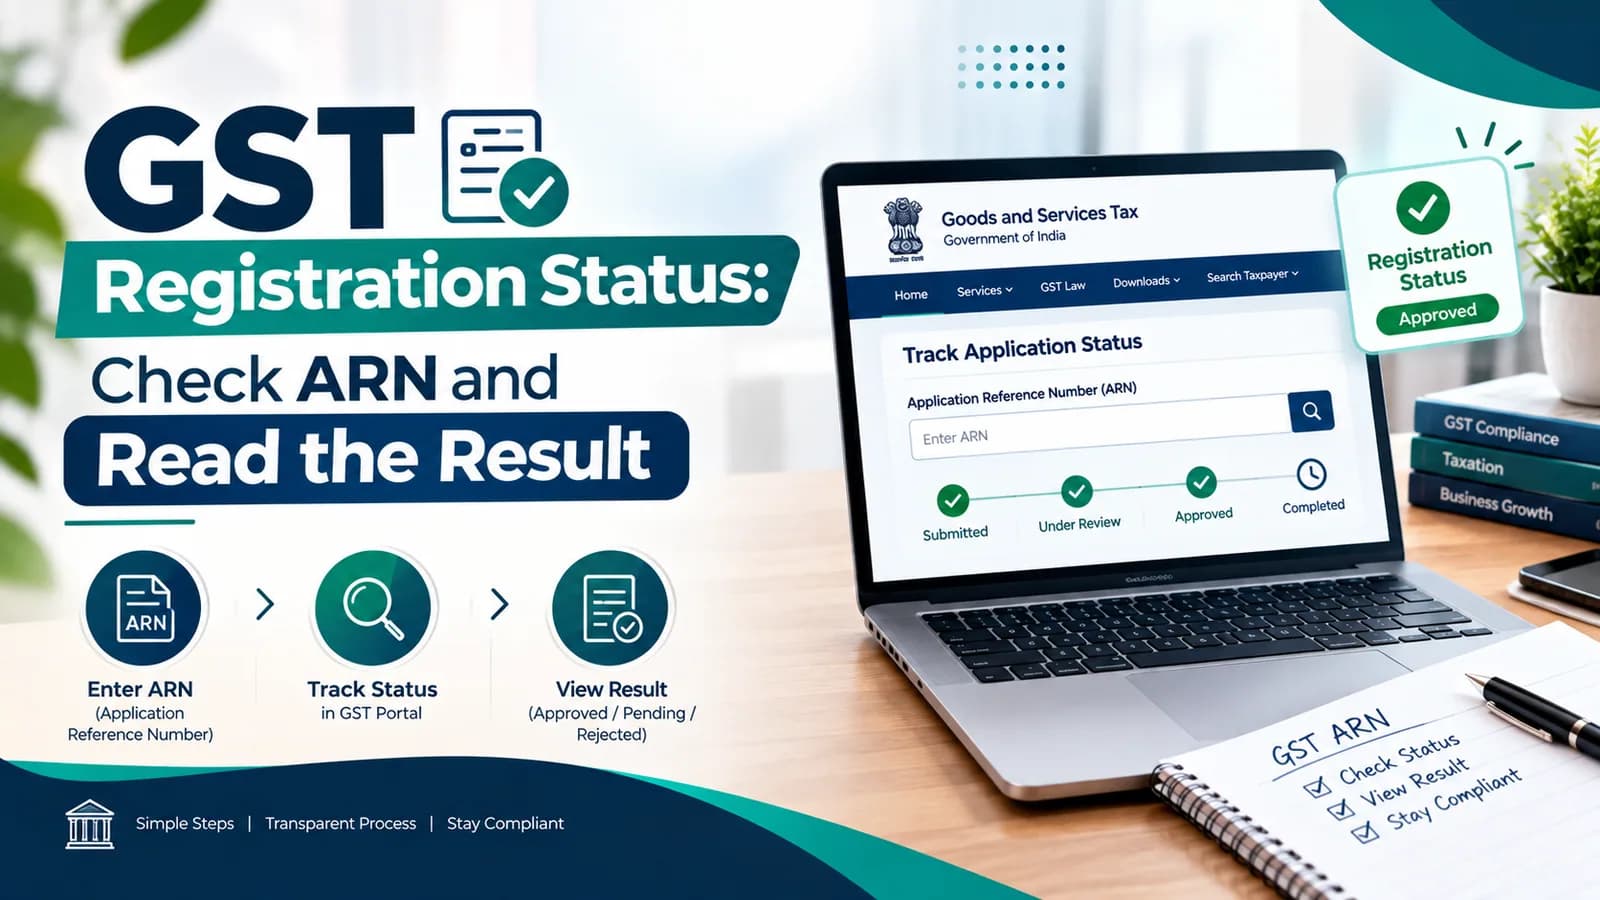
Check GST registration status on the GST portal under Services, then Track Application Status, using the ARN you received after submitting FORM GST REG-01. No login is needed. The status word the portal returns is what matters, because each one carries a different deadline and a different next step.
Key facts on tracking GST registration status
Item | Position as on 31 August 2026 |
|---|---|
Where to check | gst.gov.in, Services, Track Application Status |
What you need | ARN, or TRN if the application has not been submitted yet |
Login required | No, for ARN-based tracking |
Fee | Nil |
Normal approval window | Seven working days under Rule 9(1); three working days on the Rule 14A route |
Extended window | Thirty days where Aadhaar authentication fails or physical verification is flagged |
Time to answer a query | Seven working days from the REG-03 notice, under Rule 9(2) |
How to check GST registration status by ARN
Open the GST portal and go to Services, then Track Application Status.
Select Registration in the module drop-down.
Enter the fifteen-character ARN issued when you submitted the application.
Complete the captcha and submit to see the current stage and the date it changed.
The same screen on gst.gov.in also shows the processing history, so you can see the exact date the application moved between stages. That date is what your seven-day reply clock runs from, not the day the email reached you.
How to check status before you have an ARN
An ARN is issued only after Part B is submitted. Between Part A and Part B you hold a Temporary Reference Number, and a TRN-based application expires if Part B is not completed within fifteen days.
To resume, choose Register on the portal, select Temporary Reference Number, enter the TRN and validate the OTP. The saved application opens where you left it, showing a My Saved Application list with the expiry date against it. Let that date pass and the entire draft is deleted, including uploaded documents.
What each GST registration status means
This is the part the portal does not explain. Each status is a different situation with a different owner and a different deadline.
Status shown | What it means | What you should do |
|---|---|---|
Pending for Processing | Application submitted and sitting with the officer, not yet examined | Wait. Act only after seven working days |
Pending for Clarification | A notice in FORM GST REG-03 has been issued against your file | Reply in FORM GST REG-04 within seven working days |
Clarification filed - Pending for Order | Your reply is in and the officer has seven working days to decide | Wait and keep documents ready |
Clarification not filed - Pending for Order | The reply window has closed with no response | Expect rejection. Prepare a fresh application |
Site Verification Assigned | The file has been sent for physical verification of premises under Rule 25 | Ensure the premises are open, signposted and staffed |
Site Verification Completed | The officer has visited and filed the report | Wait for the order |
Approved | Registration granted; GSTIN and FORM GST REG-06 available on the portal | Download the certificate and add bank details |
Rejected | Application refused by an order in FORM GST REG-05 | Read the ground, fix it, and file afresh |
[VERIFY: confirm the exact status labels currently displayed on the portal before publishing this table, as GSTN has renamed some of them in past releases.]
Pending for Processing, and when waiting stops being correct
Pending for Processing means nobody has opened your file yet. Under Rule 9(1) of the CGST Rules, the officer has seven working days from submission to approve the application or issue a query.
Rule 9(5) is the part applicants rarely know. If the officer neither approves nor raises a query within that period, the application is deemed approved and the portal issues the registration automatically. So a file stuck at Pending for Processing on working day nine is not a problem you can chase; it is a deemed approval waiting to fire.
Where it stretches well beyond that, the usual cause is that the application was never really at the seven-day stage. Applications flagged for physical verification, or where Aadhaar authentication did not go through, sit on a thirty-day clock instead.
Pending for Clarification: the seven-day trap
This status means a notice in FORM GST REG-03 has been issued and the department is waiting on you. The reply goes in FORM GST REG-04 and is due within seven working days of the notice, not seven working days from when you noticed it.
Log in, open Services, Registration, Application for Filing Clarifications, and enter the ARN. The notice text appears with the specific fields the officer wants corrected. You can amend the flagged fields directly in that screen and upload replacement documents.
Answer every point raised, not the one that seems most important. A partial reply is treated as no reply on the unanswered items.
Upload the document the officer asked for, rather than a different document that proves the same thing.
Keep the address wording identical to the address proof, because a re-typed address triggers the same query again.
Submit with DSC or EVC, and confirm the status has moved to Clarification filed before closing the browser.
Address proof is behind most REG-03 notices. The wording and attachments that survive scrutiny are set out in our note on the consent letter for GST registration.
Site Verification Assigned: what the officer looks for
This status means the file has gone for physical verification of the business premises under Rule 25 of the CGST Rules. The officer visits, photographs the premises, and uploads a report in FORM GST REG-30.
Verification is triggered by risk parameters rather than by anything you did wrong: a shared or coworking address, a location with several existing GSTINs, a residential address for a goods business, or a failed Aadhaar authentication.
Keep the premises accessible during working hours for the next week, with someone who can answer basic questions.
Put up a signboard with the entity name at the address you declared.
Keep the original address proof, consent letter and PAN available at the location.
Do not send the officer to a different branch, because the report is filed against the declared address only.
Approved: the three things to do immediately
Once the status reads Approved, the GSTIN is live and the registration certificate in FORM GST REG-06 is available on the portal under Services, User Services, View or Download Certificates. There is no physical certificate and none is posted to you.
Download REG-06 and check the effective date of registration, the principal place of business, and every additional place listed.
Add bank account details, which are due under Rule 10A within thirty days of registration or before your first FORM GSTR-1, whichever is earlier.
Display the certificate at the principal place of business and every additional place, and put the GSTIN on the name board, as Rule 18 requires.
Rejected: what your options actually are
Rejection comes as an order in FORM GST REG-05 and always carries a stated ground. Read the ground before doing anything else, because it decides whether you refile or appeal.
Most rejections are document failures rather than eligibility failures, and the correct response is a fresh FORM GST REG-01 with the defect fixed. There is no restriction on reapplying and no cooling-off period. Where the rejection is on a point of law you disagree with, an appeal lies to the Appellate Authority under Section 107 within three months.
Refiling with the same defective document is the most common reason a second application fails too. A GST amendment cannot repair a rejected application, because there is no registration to amend.
How long each stage normally takes
Stage | Normal duration | Governing provision |
|---|---|---|
Part A to TRN | Immediate | Rule 8(1) and 8(2) |
TRN valid for Part B | Fifteen days | Portal rule |
Submission to approval, standard route | Seven working days | Rule 9(1) |
Submission to approval, Rule 14A route | Three working days | Rule 9A |
Aadhaar failed or verification flagged | Up to thirty days | Proviso to Rule 9(1) |
REG-03 notice to REG-04 reply | Seven working days | Rule 9(2) |
Reply to final order | Seven working days | Rule 9(3) |
The three-working-day route came in through Notification No. 18/2025-Central Tax dated 31 October 2025. Whether you should take it depends on your state plans, which our guide to Rule 14A GST registration works through.
What the status screen does not tell you
The portal shows a stage, never a reason. An application sitting at Pending for Processing on day twelve and one flagged for verification look identical until the status changes, which is why applicants chase the wrong problem.
[EXPERT INPUT NEEDED: Keshav - one real anonymised case where a status stalled or moved unexpectedly. What stage it sat at, what the underlying cause turned out to be, and how we resolved it.]
Application stuck, or a REG-03 notice you are not sure how to answer? Talk to Keshav’s team at Complylocal about GST registration services.